Market Pulse
While tariffs have created significant uncertainty across the industrial economy, the data suggests many companies have been more successful at protecting profitability than initially expected. Beneath the surface, however, a clear divide has emerged: Suppliers of critical materials, components and subassemblies have generally strengthened pricing power and expanded margins, while finished product providers have faced a more challenging environment. The analysis below examines how value-chain positioning influenced margin performance through the tariff period and what the results mean for owners, investors and acquirers.
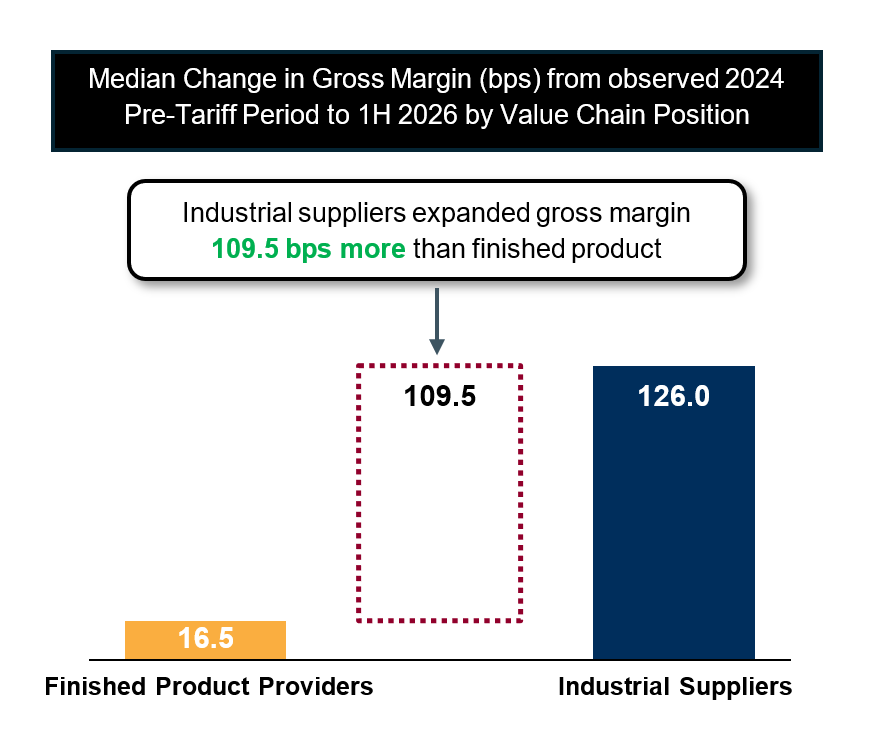
M&A Market Snapshot
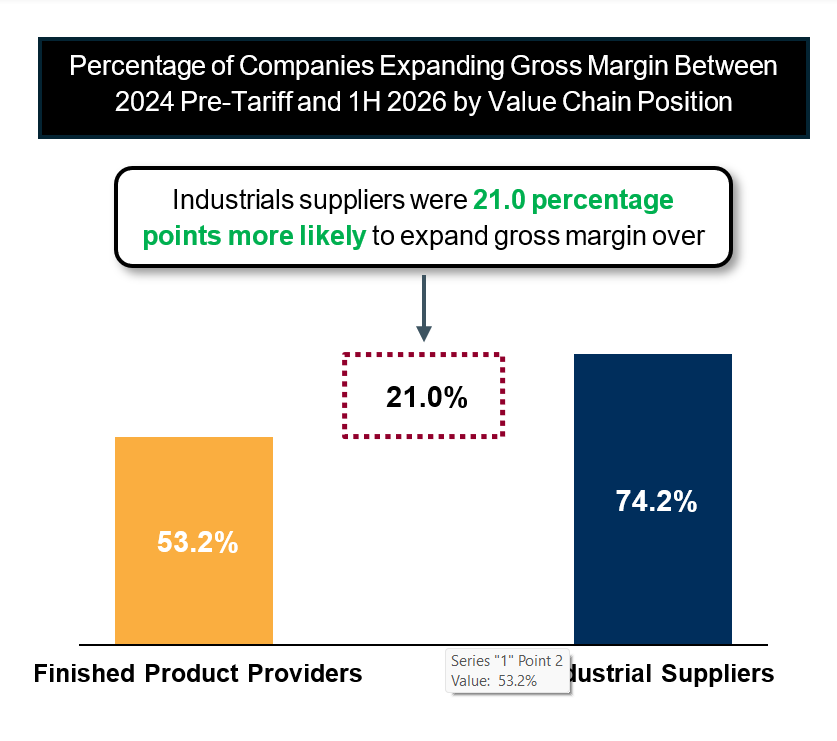
Industrial suppliers of materials, components and subassemblies outperformed finished product providers through the tariff period. From pre-tariff levels (CQ3–CQ4 2024) to 1H 2026, median supplier gross margin expanded 126.0 bps, versus 16.5 bps for finished product providers. The advantage was also broad-based: 74.2% of suppliers improved margins, compared with 53.2% of finished product providers.
Margins rose for both groups, so tariffs did not broadly compress industrial profitability. Because passing through costs dollar-for-dollar would actually lower margin percentages, the gains mean pricing outpaced costs. Suppliers captured more of that benefit. Their products are often designed into customer specifications and hard to replace quickly, and many repriced through surcharges and index-linked contracts. Finished product providers faced more visible, contested pricing with their customers and more competition from imports, which limited how much cost they could recover.
What does this mean for owners and acquirers
Valuation. Buyers will ask how much of recent margin improvement is durable. Gains tied to tariff surcharges may reverse if policy shifts, while gains from genuine pricing power will hold. Companies that can clearly show the difference will command stronger valuations.
Positioning. The results reinforce the value of being hard to replace. Finished product providers may look to acquire or partner with critical component suppliers to protect margins and secure supply. Investors are likely to favor supplier businesses with demonstrated pricing power as acquisition platforms.
Timing. Owners of suppliers with strong results are in a favorable position to explore a sale or recapitalization while the performance is fresh. Finished product providers under margin pressure may find that scale through combination is the most direct path to recovering pricing leverage.
Value-chain position is not a guarantee. Roughly a quarter of suppliers did not expand margins. The strongest companies will be those whose gains reflect lasting advantages rather than temporary tariff effects.
About Intrepid Investment Bankers
Intrepid Investment Bankers is a leading middle-market investment bank providing M&A, capital raising, and strategic advisory services. As part of MUFG, one of the world’s largest financial institutions, Intrepid combines deep industry expertise, senior-level execution, and global resources to help clients achieve their strategic objectives.
Connect with Intrepid
Questions about market conditions, valuations, capital raising, or transaction activity? Intrepid’s team is available to discuss the trends shaping today’s M&A environment and what they may mean for your business.